Introduction
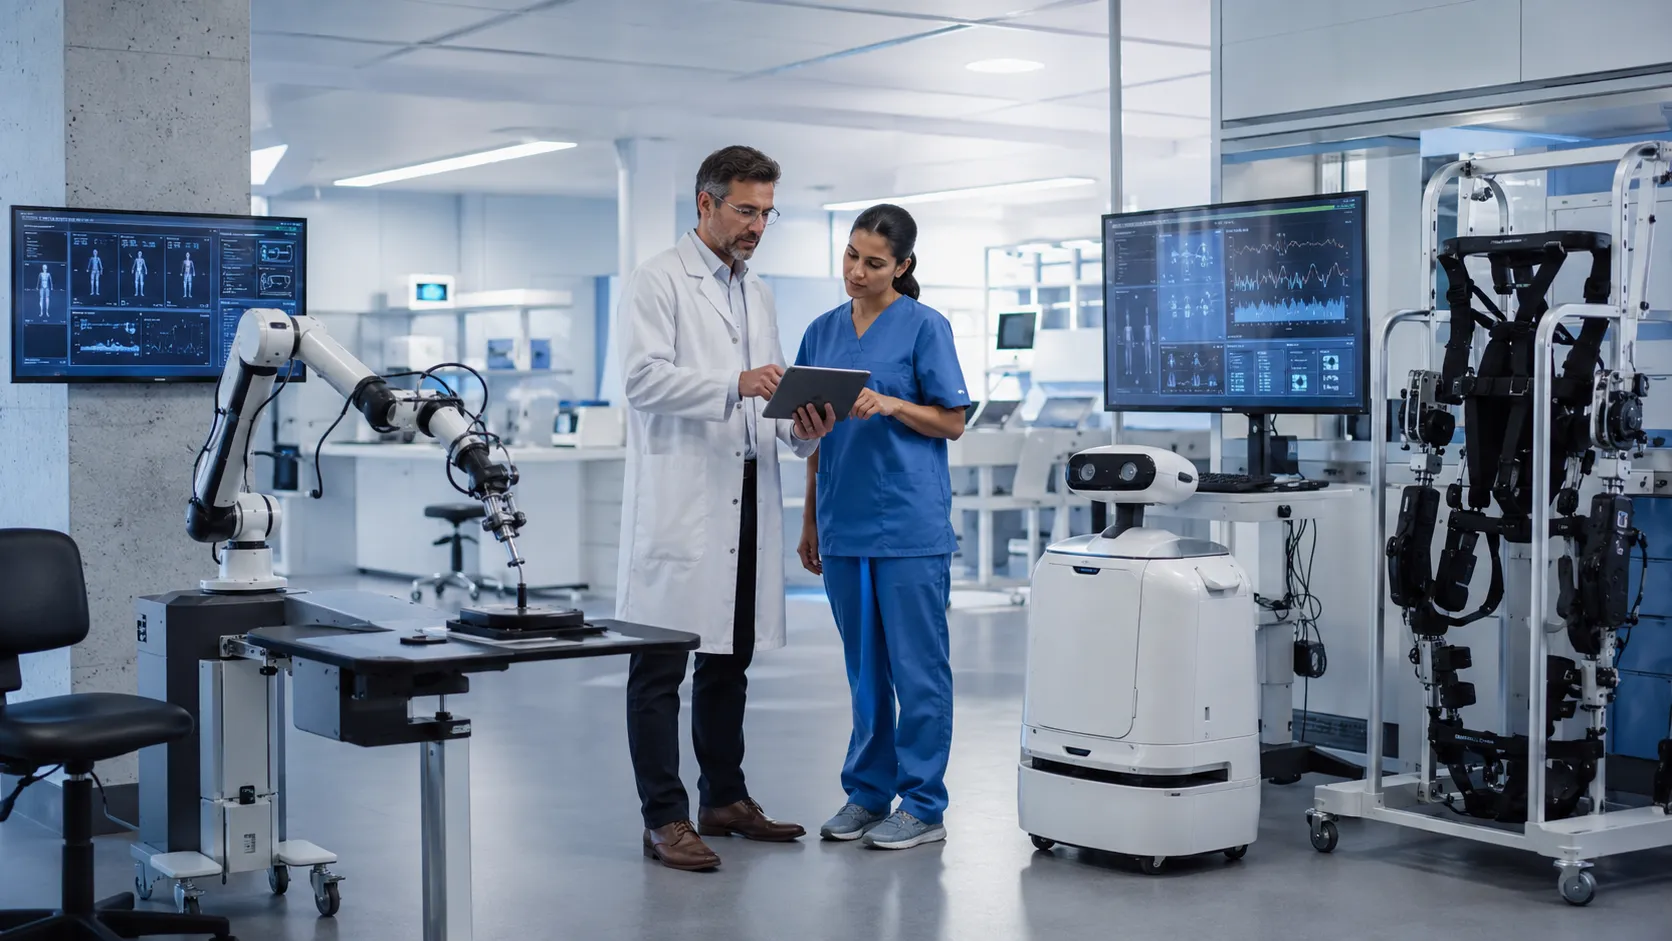
Artificial intelligence and robotics have moved from the margins to the mainstream of medical equipment in a remarkably short time. AI-assisted imaging, robotic surgery platforms, autonomous laboratory systems and intelligent monitoring are already in clinical use in hospitals around the world. The question for buyers, suppliers and healthcare planners is no longer whether these technologies will arrive — it is how quickly they will move from specialist to standard, and what that means for procurement, investment and patient care.
This guide looks at where AI and robotics in medical equipment stand today, what the near- and medium-term developments look like, the challenges that must be overcome, and what it all means for anyone buying, selling, or planning medical equipment across the UK, Europe, the US, the Gulf, and South Africa.
Where AI and robotics stand today
Both technologies are already in clinical use, though adoption is uneven across facilities, specialities, IEs, and geographies.
-
AI in diagnostics — AI-assisted analysis of radiology images, pathology slides and ECGs is commercially available and in routine use in leading facilities. These systems augment rather than replace human specialists.
-
AI in monitoring — continuous patient monitoring with AI-driven early warning scoring is being deployed in ICUs and high-dependency units, alerting staff to deteriorating patients before clinical signs become obvious.
-
Surgical robotics — robotic-assisted surgery platforms are in routine use for prostatectomy, colorectal, gynaecological and some orthopaedic procedures. Single-port robotic systems are extending the range of procedures accessible through minimal access.
-
Robotic laboratory automation — track-based laboratory automation links analysers, reduces manual handling and shortens turnaround times in high-volume hospital laboratories.
-
AI regulatory recognition — most major regulators now have specific frameworks for AI and Software as a Medical Device, with the FDA, MHRA and European Commission all publishing guidance on how AI devices are assessed.
What is coming next: near-term developments
Several developments currently in clinical trials or early commercial deployment are likely to achieve broader clinical adoption within three to five years.
-
Closed-loop clinical systems. AI that not only detects a problem but initiates a controlled response — adjusting ventilator settings, delivering insulin, modulating anaesthesia depth — with physician oversight rather than physician action for every change.
-
Autonomous robotic surgery. Surgical robots that can perform defined, repetitive sub-tasks autonomously — suturing, tissue dissection — while the surgeon supervises. Full autonomous surgery remains a distant prospect, but task-level automation is closer.
-
AI pathology and histology. Whole-slide digital pathology with AI analysis is moving from research to clinical use, enabling faster, more consistent diagnosis and remote pathology reporting without physical slide transport.
-
Wearable diagnostics. Wearable devices that provide continuous monitoring of biomarkers beyond heart rate and oxygen saturation — glucose, blood pressure, cardiac rhythm, temperature and more — using non-invasive sensing.
-
Micro and nanorobotics. Miniaturised robotic devices capable of targeted drug delivery, minimally invasive biopsy or repair of structures inaccessible to conventional instruments are advancing through research and early clinical investigation.
AI and robotics adoption by region
Investment, the regulatory environment, and healthcare infrastructure drive the adoption of AI and robotics in medical equipment.
|
Region |
AI adoption |
Robotics adoption |
|
North America |
Advanced — leading deployment |
High — the largest robotic surgery market |
|
Europe |
Steady — EU MDR pathway developing |
Growing — strong in Germany, the UK, and France |
|
Asia-Pacific |
Rapid — China and Japan leading |
Fast-growing — local manufacturers are emerging |
|
Gulf (GCC) |
Accelerating — new facilities adopting |
Investment-driven — new hospitals buying the latest |
|
Africa |
Early portable AI tools pioneering |
Very limited — cost and infrastructure barriers |
China and Japan are significant forces in AI medical device development and adoption. Local Chinese AI medical device manufacturers are competing directly with US and European companies in many Asian and emerging markets.
Challenges that will shape the pace of change
-
Regulation keeping pace with technology — regulatory frameworks for AI devices are still maturing. Adaptive AI systems that learn from data after deployment present challenges that traditional regulatory models were not designed to handle.
-
Evidence and clinical validation — AI systems require robust evidence of clinical validation across diverse patient populations. Bias in training data can lead to systems that perform worse for some demographic groups.
-
Integration and interoperability — AI and robotic systems need to integrate with existing hospital IT infrastructure, electronic health records and workflows. Poor integration limits clinical adoption regardless of technical performance.
-
Cost and access — robotic surgery systems and advanced AI diagnostics are expensive, limiting adoption to well-funded facilities and creating potential equity issues in access to technology-enhanced care.
-
Workforce and training — the adoption of AI and robotics changes the skill requirements for clinical and technical staff. Training and change management are as important as the technology itself.
Planning your AI and robotics equipment investment?
We help hospitals navigate technology-forward procurement across the UK, Europe, the US, the Gulf and South Africa. Tell us the clinical area and the technology horizon you are planning for — we will help you find devices that are approved, supported and future-ready.
No pressure, no obligation. → Talk to the team
What AI and robotics mean for medical equipment procurement
For procurement teams, AI and robotics create new evaluation criteria alongside the traditional ones. A diagnostic AI system requires assessment of the clinical evidence base, the diversity of the training data, the regulatory approval pathway, the update and maintenance model, and the integration requirements — none of which appear in a conventional equipment specification.
Robotic surgical systems require evaluation of the case volume justification, the surgeon training and credentialing pathway, the consumable costs per procedure, and the manufacturer's long-term service and upgrade commitment. These are investment decisions that span the clinical, financial, technical and strategic dimensions of the organisation.
What the AI and robotics future means for buyers and suppliers
-
Buyers. Plan for a technology horizon, not just a purchase. AI and robotic equipment require investment in integration, training and ongoing management beyond the initial purchase. Build these costs and commitments into the procurement case.
-
Suppliers. The market for AI and robotic medical equipment is growing fast, but so is the scrutiny. Clinical evidence, regulatory approval, integration capability and long-term support are the differentiators that matter most to informed buyers.
-
Everyone. AI and robotics will not replace clinical judgment — they will change the tools through which it is applied. Understanding that distinction matters for everyone involved in medical equipment.
More from Business
-
Buyers — source AI-assisted and technology-forward medical equipment from a worldwide supply base.
-
Suppliers — list your AI and robotics-enabled devices and reach hospital buyers planning technology investments.
-
Advertise — promote your products and services to a clinical audience.
-
Business overview — explore everything MediGear offers healthcare organisations.
Disclaimer
This article is for general information only and does not constitute clinical, procurement, regulatory, financial or technology advice. AI and robotic medical device development, regulatory frameworks and market availability change rapidly. Always verify that any device is approved for your market and consult qualified clinical, biomedical engineering and procurement professionals for decisions specific to your facility. medigear.UK accepts no liability for actions taken based on this content.
**Market figures are indicative ranges drawn from multiple published market research sources and vary across definitions and methodologies. ****
Planning for next-generation equipment?
We supply current and emerging medical equipment to hospitals and procurement teams across the UK, Europe, the US, the Gulf and South Africa. Tell us what you need — we will help you plan the right technology investment.
Frequently Asked Questions
AI is used in medical equipment for diagnostic image analysis in radiology and pathology, early warning and deterioration detection in patient monitoring, drug dosing and error reduction in smart infusion pumps, and clinical decision support in point-of-care diagnostics. AI software that makes or influences clinical decisions is regulated as a medical device and requires regulatory approval before clinical use.
Robotic surgery uses a surgeon-controlled robotic platform to perform minimally invasive procedures with greater precision and range of motion than conventional laparoscopy. It is used in urology, colorectal, gynaecological, thoracic and some orthopaedic and cardiac procedures. Major academic and specialist hospitals in North America, Europe and increasingly Asia use robotic platforms. The capital and consumable costs remain high, limiting adoption in smaller and resource-limited facilities.
No. AI in medical diagnostics is designed to augment human clinical judgment, not replace it. Current AI systems assist by detecting patterns in imaging, pathology, or monitoring data and flagging findings for clinical review. They work alongside radiologists, pathologists and clinicians rather than independently. Regulatory frameworks in all major markets require human oversight of AI clinical decisions, and the evidence for fully autonomous clinical AI remains limited.
AI and Software as a Medical Device is regulated in most major markets — the FDA in the US, the MHRA and CE marking in the UK and EU, and SFDA and SAHPRA in the Gulf and South Africa. The FDA has published a specific AI/ML action plan and issued 510 (k) clearances or PMAs for AI diagnostic software. The EU MDR applies to software intended to make or influence clinical decisions. Regulatory requirements vary by the risk level of the AI's clinical function.
Robotic laboratory automation uses track-based conveyor systems and robotic arms to transport samples between analysers, perform sample preparation, and manage storage and retrieval — all without manual handling. This reduces turnaround time, minimises human error, improves throughput and allows laboratories to operate more efficiently with fewer staff. Total laboratory automation is most cost-effective in high-volume hospital laboratories.
Wearable medical devices are moving from consumer health tracking toward clinical-grade continuous monitoring. Future wearables are expected to monitor an expanding range of biomarkers non-invasively — blood glucose, blood pressure, cardiac rhythms, inflammatory markers and more — feeding continuous data to clinicians and AI systems for earlier detection of deterioration, better chronic disease management and reduced hospital admissions.